Tarp and repair
$350–$3k
- Same-day emergency tarp
- Photo report of every slope
- Wind-lost shingles replaced
- Dented vents and caps swapped
- Torn flashing refastened
- Loose tabs hand-sealed

Storm damage roof repair · Hail · Wind · Insurance claims
After hail or high wind, a roofer inspects the same day when the schedule allows, tarps any opening and photographs every slope, vent and gutter. You get a written damage report you can hand to your insurer, and we meet the adjuster on the roof if you file a claim.
We never ask you to sign anything on the first visit, never offer to cover your deductible and never pressure you to file a claim.
What happens after you text us
This is a typical exchange the morning after hail. You tell us what you see, we ask for a photo of the vents or the car, and you get an inspection time plus plain advice on whether to call your insurer yet.
We had golf ball hail last night. Three different roofing companies knocked on our door already this morning. How do I know if the roof is actually damaged?
Hi Jen, Tony here with ProBuild Remodeling, we are local. Do not sign anything with anyone yet. Can you text me a photo of the metal vents on the roof or the gutter? Dents there usually mean the shingles took hits too.
Sent. The gutter has dents all along it and the car has some too.
That size of dent often bruises shingles. I can inspect at 3 today and photograph every slope. If I find damage, call your insurer with the report, and I will meet the adjuster on the roof if you want me there.
3 works. Do I need to call the insurance company before you come?
No, better to know first. If nothing is damaged, you avoid a claim on your record. See you at 3.
What storm damage repair costs
Prices are the full cost of the work before any insurance payment, for a typical two-story asphalt roof. If a claim is approved, you usually pay only your deductible and anything you choose to upgrade.
Tarp and repair
$350–$3k
Slope replacement
$3k–$9k
Full replacement
$10k–$30k
Choose how much of the roof was hit, the height of the house and its age. The range updates instantly, showing the full cost before any insurance payment.
A range, not a quote. Your written estimate comes after the visit and does not change once you approve it.
Typical range for your answers
Book an inspection to document the damageWhere the money goes
Averages from our recent storm replacements. First adjuster estimates often leave out code-required items like drip edge and ice barrier, or dented gutters and vents. We document them so they can be added through a supplement.
Get my itemized storm damage report
File a claim or pay yourself
A claim goes on your record even when the payout is small. After the inspection we write down the damage and what fixing it costs, so you can compare it with your deductible before calling your insurer.
| If this is true | Our advice |
|---|---|
| Repair costs less than your deductible | Pay yourself |
| Hail bruised shingles on three or more slopes | File a claim |
| Wind took a dozen shingles and nothing else | Pay yourself |
| A tree broke through the deck or rafters | File a claim |
| The damage looks older than this storm | Pay yourself |
| Gutters, vents and siding were hit as well | File a claim |
How it unfolds
Stopping water comes first and never waits for the insurer. After that, timing depends on your adjuster's visit, usually one to three weeks after you file, and the repair itself takes one to four days.
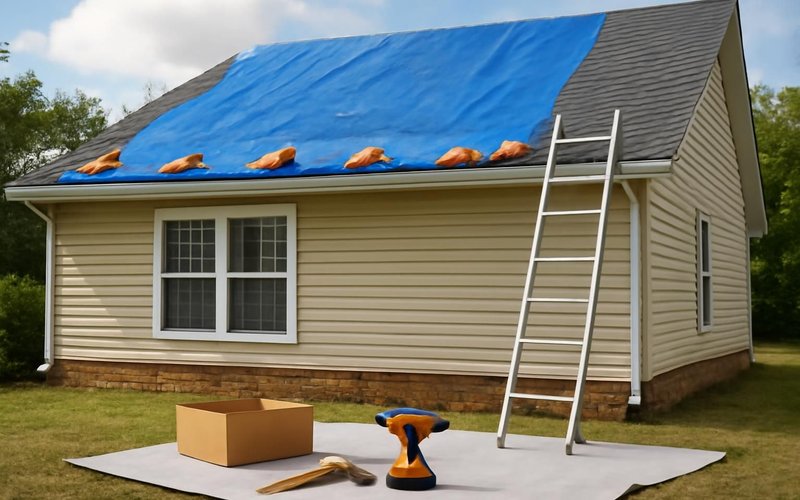
Day of the storm
Openings tarped or boarded, water inside contained, first photos taken before anything is moved.
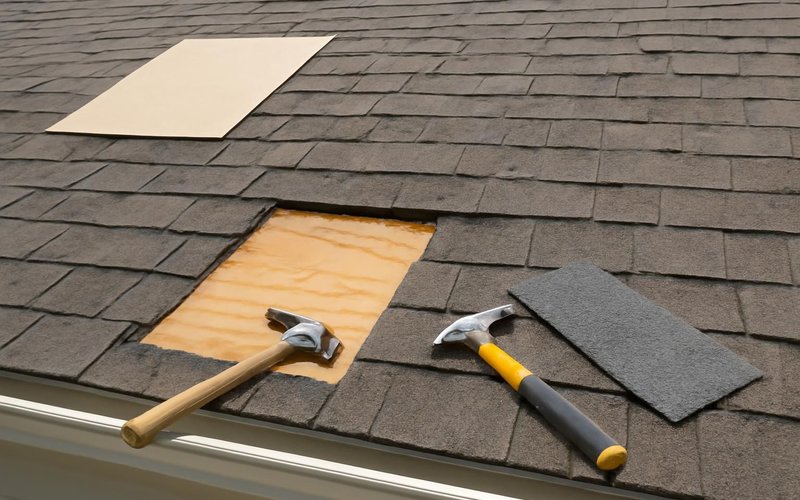
Within days
Every slope, vent, gutter and window screen photographed and marked, with a written report you keep.
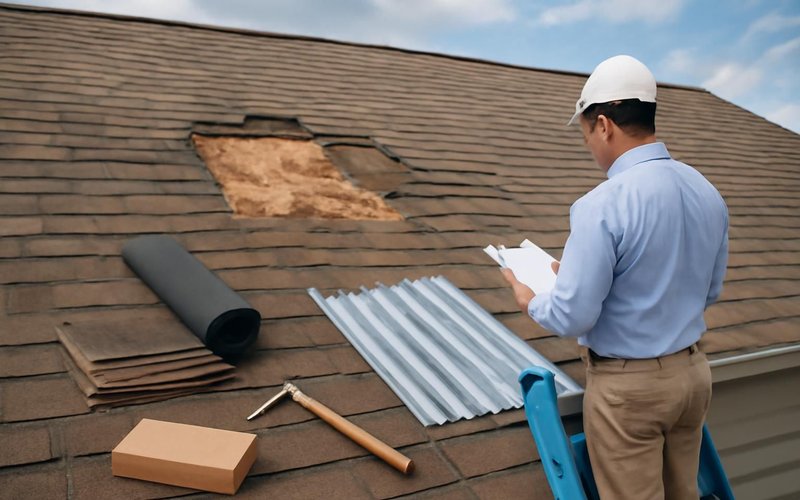
Adjuster visit
We walk the roof with your adjuster, point out each hit and send any missed items as a written supplement.
Repair days
Repair or replacement done to code, final photos and invoice sent to you and your insurer for payment.
Remodeling concepts
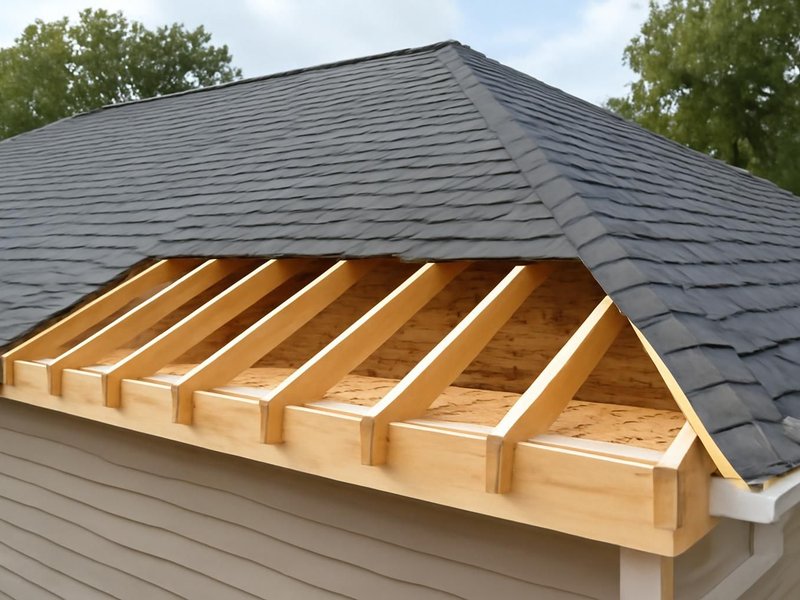
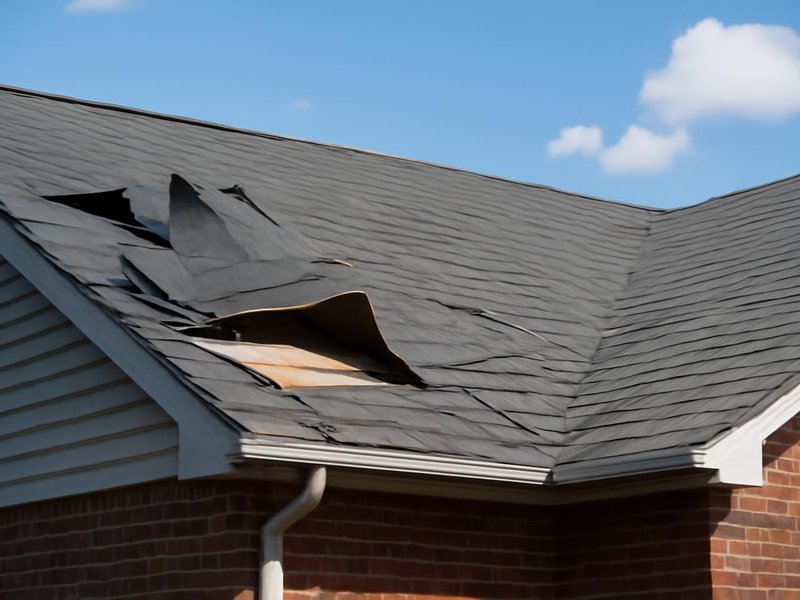
AI-generated examples of existing conditions and remodeling possibilities. Each image is a separate concept, not a documented transformation of the same home.
What storm repairs use
A storm repair done with leftover shingles and roof cement fails in the next storm. Everything below is named on your invoice and in the file your insurer receives.
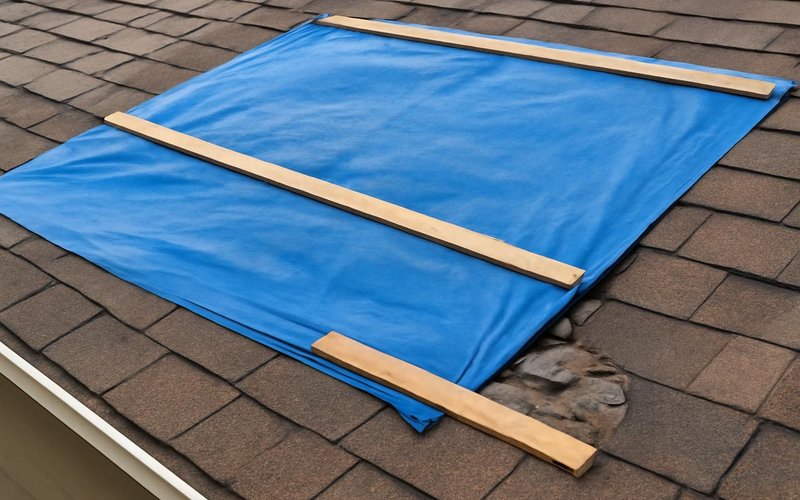
Heavy woven tarps battened with wood strips and screwed over the ridge, rated to stay put in wind until the repair can be made.
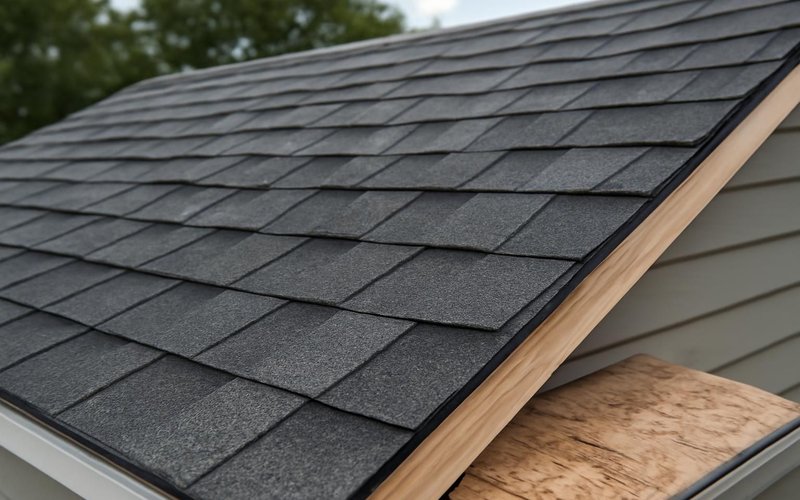
Lines like Owens Corning Duration Flex or GAF Timberline AS II. Offered as an upgrade on storm replacements in hail country.
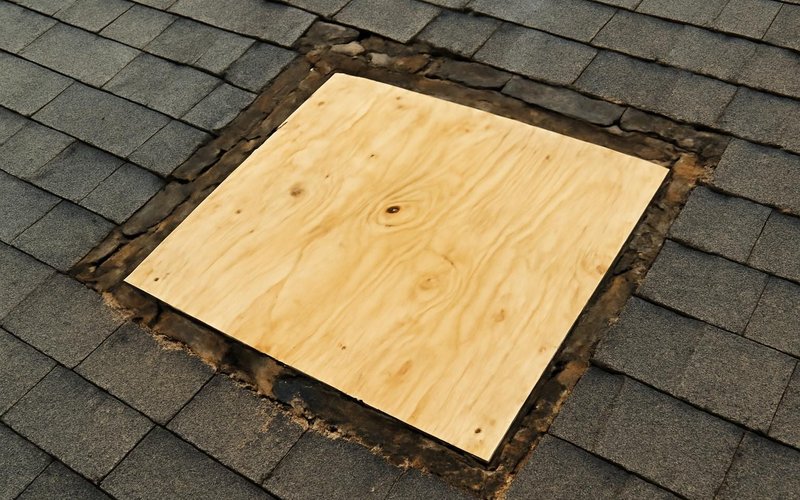
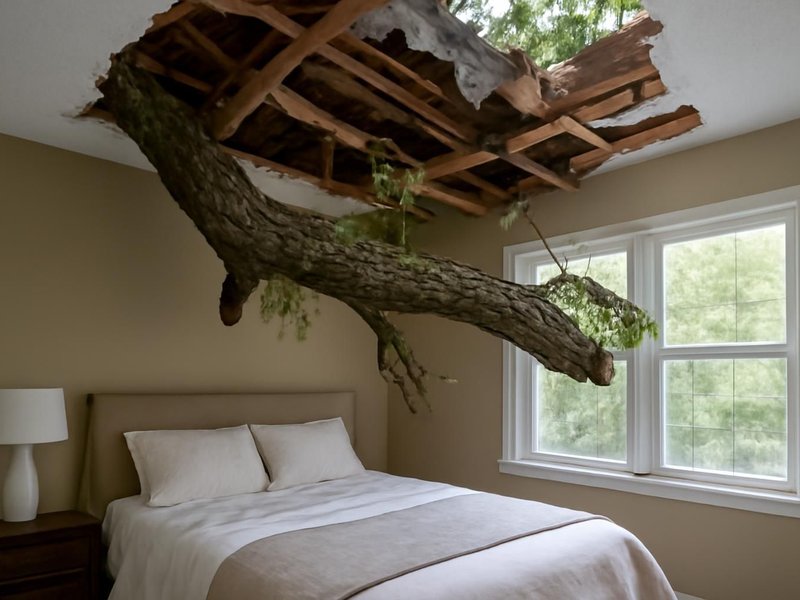
Where a limb broke the deck, we close the hole with plywood fastened to the rafters before the tarp, so rain cannot pool.
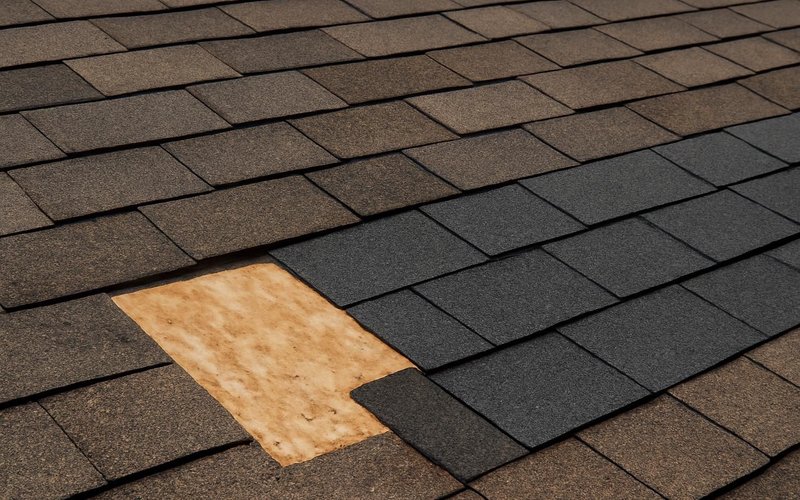
Replacement shingles matched by brand, line and color. If your line is discontinued, we document it for your insurer.
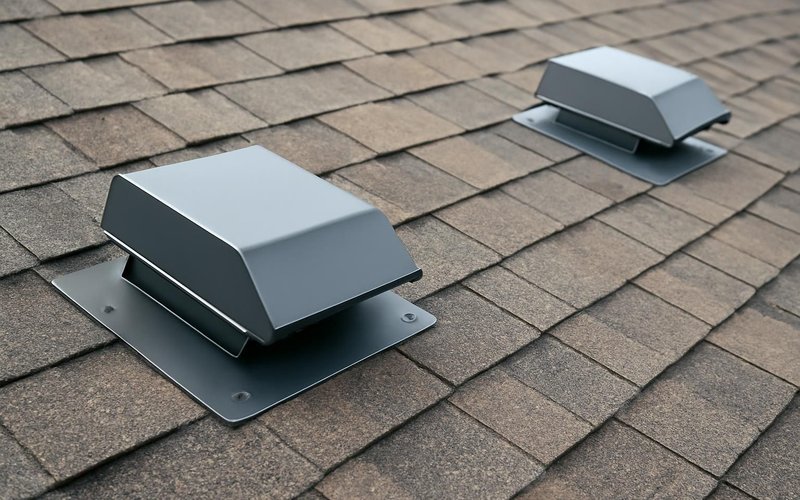
New box vents, ridge vent and exhaust caps to replace dented ones, in the same size so they seal to the existing flashing.
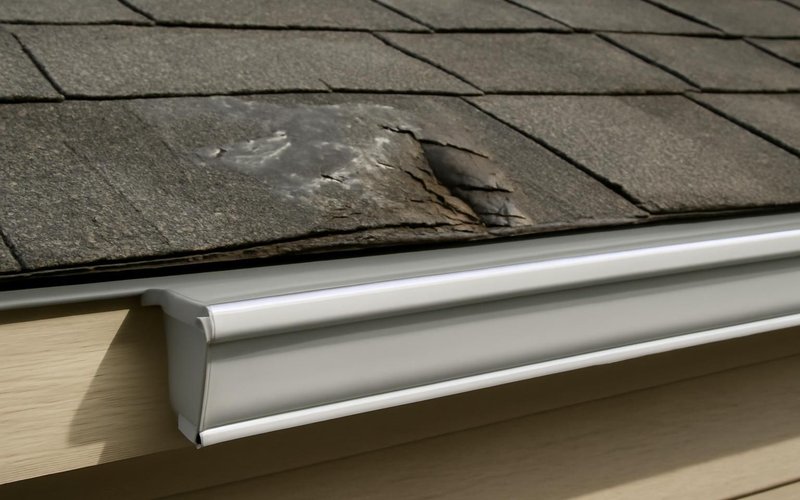
Dented aluminum gutter runs and downspouts replaced in matching color and profile, often part of the same storm claim.
Written into every contract
The approved price is the final price. Change orders only with your written approval.
A credit for every working day of delay we cause. Weather and inspections excepted, in writing.
Dust barriers, floor protection and a clean-up before we leave. Your home stays livable.
A text or email every working day with photos and tomorrow's plan, or the day is free.
Workmanship warranty in writing, transferable to the next owner, backed by a fixed address.
A small deposit, then you pay only for work that is already completed, inspected and photographed.
Who shows up after the storm
After big storms, out-of-town crews knock on doors and leave when the work dries up. Our storm team works under the license of your state, is background-checked, and will still answer the phone when you need a warranty call.

Documents every slope and writes the report for your insurer.

Tarps openings the first day and leads the repair or rebuild.

Keeps the photos, supplements and invoices your insurer needs.
Illustrative project scopes
Planning examples with illustrative budgets and durations. These are not completed customer jobs, invoices or promises about your project.
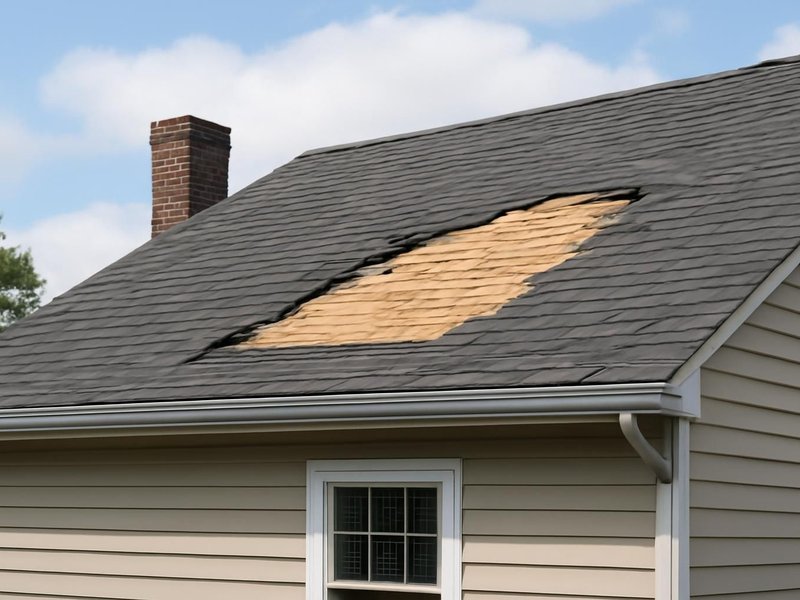
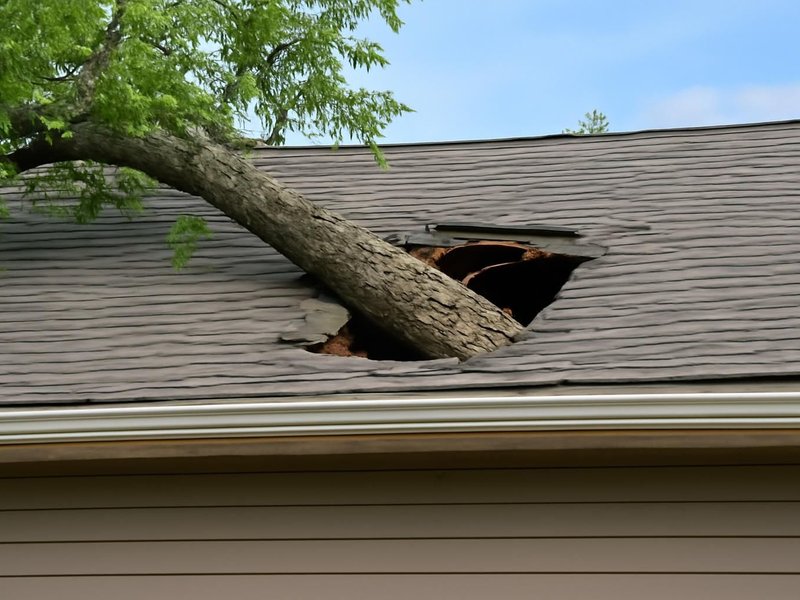
Your storm is not average
The first job is always the same: stop the water. After that, what we do depends on the storm, the insurer and the house. Pick the case closest to yours.
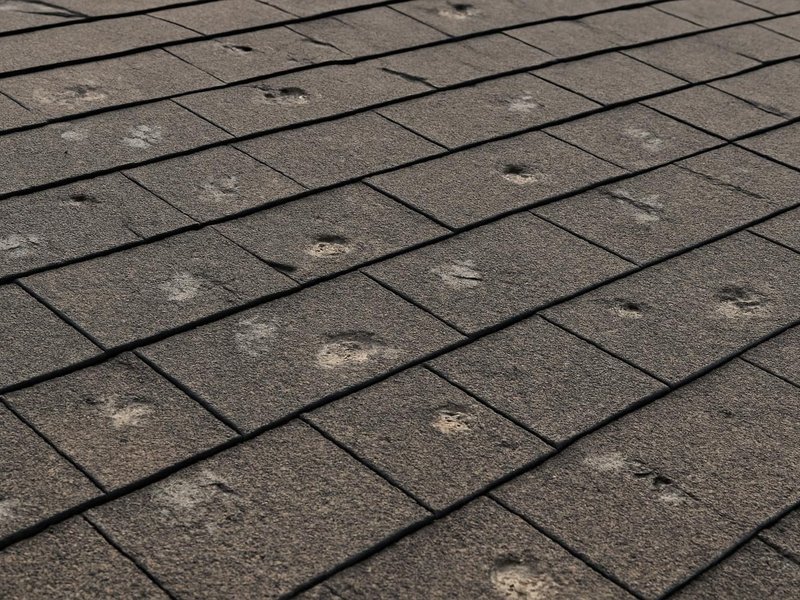
Hail damage is easy to miss from the ground and often shows up months later as leaks. We inspect every slope, mark hits on a test square the way adjusters do, and tell you honestly if the damage is not worth a claim.
Book my hail damage inspectionDo not go on the roof or into the attic under the limb. We coordinate the tree removal, board and tarp the opening the same day, check the rafters for cracks and document all of it for your insurer before rebuilding.
Book my emergency tree damage visitIf the adjuster's estimate looks low or misses items, send it to us. We compare it with our own photos line by line, and send any missed code items or damage to your insurer as a documented supplement.
Review my adjuster's estimateAfter a named storm, crews and tarps run short everywhere. We tarp storm openings first, then schedule repairs in order of risk. Rebuilt sections follow your county's high-wind nailing and inspection rules.
Book my hurricane roof inspectionWhen an older roof takes storm damage, insurers may pay actual cash value, which subtracts depreciation for age. We explain your policy's terms in plain words and price the roof so you know your share.
Get my older roof storm estimateMany storm repairs cost less than a deductible. In that case we simply fix the damage at a fair price, with photos, and skip the claim, so nothing goes on your record for a repair you could pay yourself.
Get my storm repair priceTenants often report damage late. We inspect with or without you there, tarp the opening, send photos and a written report the same day, and arrange access with the tenant directly for the repair itself.
Book my rental storm inspectionCrews that follow storms often push a contract on the very first visit. Ours comes with none. You get a written report and a price, and you decide after comparing it with any other offer on the table.
Get my no-contract storm reportWhat this service is
Storm damage roof repair is the emergency protection, documentation and repair of a roof damaged by hail, wind, a hurricane or a falling tree, usually alongside a homeowners insurance claim. ProBuild Remodeling performs it with local licensed roofers who tarp openings, photograph every slope for your insurer, meet the adjuster and repair or replace the roof to code.
The service covers emergency tarping and board-up, a written damage report with photos, attending the adjuster inspection, supplements for missed or code-required items, and the repair, slope replacement or full replacement. It does not include negotiating your claim for you, which only you or a licensed public adjuster may do, or interior repairs unless added.
It is for homeowners whose roof was hit by a recent storm, whether or not they plan to file a claim, and for landlords with damage reported by tenants. It is not for roofs worn out by age with no storm damage, which insurance does not cover; for those we say so honestly and quote a replacement instead.
Questions we hear after every storm
Most policies cover sudden damage from hail, wind and falling trees, minus your deductible. They do not cover wear, age or poor maintenance. Older roofs may be paid at actual cash value, which subtracts depreciation. Your insurer makes the coverage decision.
Look for dents in gutters, downspouts, roof vents and car hoods, and granules piling at downspout outlets. Hits on shingles are hard to see from the ground. A roofer checks each slope and circles hits on a test square, the same way adjusters count them.
A roofer first, in most cases. An inspection tells you whether there is real damage and roughly what it costs, so you do not open a claim for damage below your deductible. If water is coming in, protect the house and call both the same day.
It depends on your policy and state, often one to two years, and some policies are shorter. Hail damage can take months to leak, so inspect soon after the storm and read the claim deadline in your policy. Waiting can weaken the claim.
No. Covering or rebating a deductible is insurance fraud and is illegal in several states. A contractor who offers it is a red flag. We charge the same price whether insurance pays or you do, and we never inflate an estimate.
Stay off the roof. Move valuables away from leaks, catch water in buckets and photograph damage inside and out. Call a roofer for tarping, then your insurer if damage is significant. Keep receipts for emergency repairs, since most policies reimburse them.
A crew that follows storms from state to state and leaves once the claims are paid. Warning signs are door-to-door visits, out-of-state plates, pressure to sign on the spot and offers to cover your deductible. Ask for a local address and a state license number.
Yes. We meet the adjuster on the roof, point out every hit and share our photos. We cannot negotiate your claim, which state law reserves for you or a licensed public adjuster, but we send documented supplements for missed or code-required items.
Storm damage roof repair near you
Storm repairs are done by local roofers licensed in your state, who will still be here after the storm season ends. License numbers are listed state by state.
Same-day storm inspection
Tell us what the storm did and a roofer texts back within 5 minutes during business hours, with a tarping or inspection time and no contract to sign.